 Ichimuhan


EUR/USD typically moves somewhere between 60 and 100 pips in an average day, though that range compresses in quiet conditions and can roughly double or more around a genuinely volatile session. There's no fixed number. What actually matters is that the range isn't flat across the day, and treating it as one constant figure is where a lot of stop and target sizing goes wrong. If the word itself needs a quick definition first, here's exactly what a pip is and why it's the standard unit on this pair.
EUR/USD typically moves 60 to 100 pips in an average day, but that figure is a sum of very unequal parts: a quiet Tokyo open can hand you a fraction of it, and the London/New York overlap can double it inside a couple of hours.
Why the average hides more than it tells you
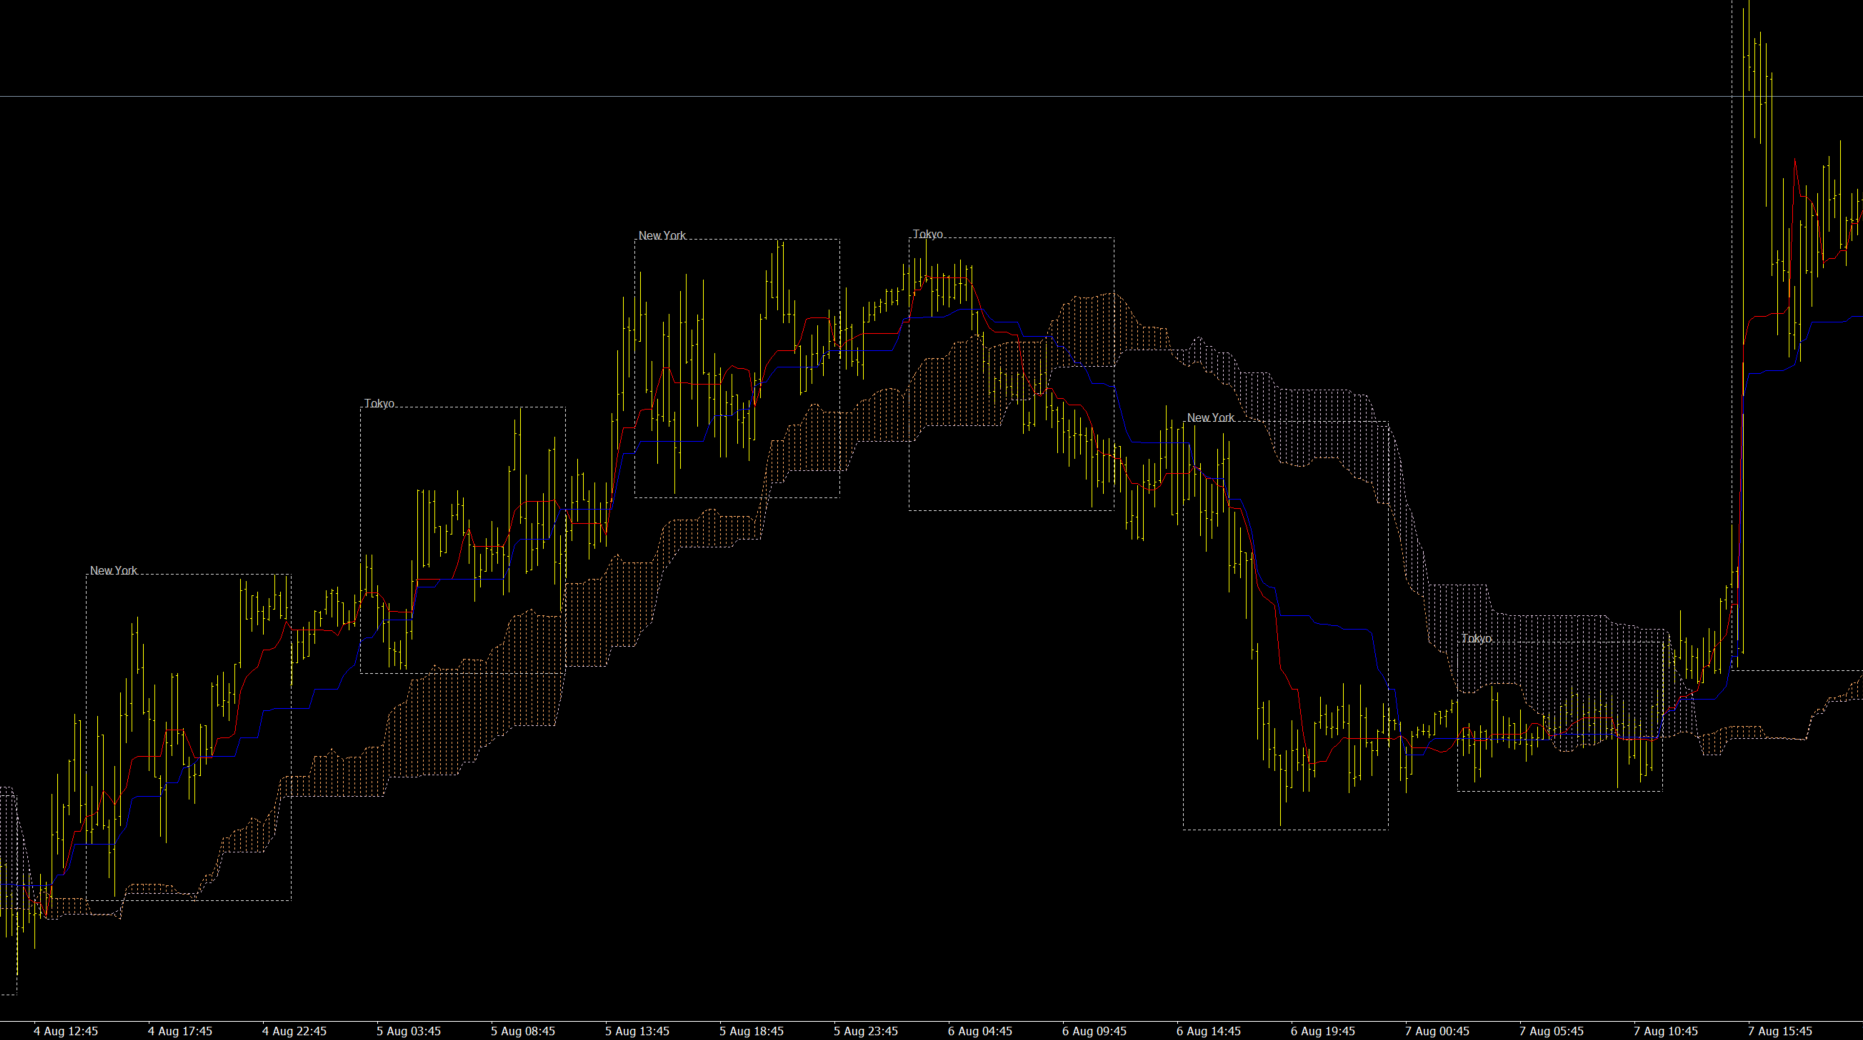
A daily average is a sum of very unequal parts. The Tokyo session typically contributes a smaller slice of the day's total range than the London/New York overlap does. Liquidity is thinner at Tokyo's open, and the overlap window is where the day's real range usually gets made. Two forecasts published for the same pair at different session opens can reasonably expect very different amounts of room to work with, which is exactly why the desk doesn't publish one call and stretch it across the whole day.
Why EUR/USD specifically behaves this way
EUR/USD is the most heavily traded spot pair in the world, at roughly a fifth of global foreign exchange turnover. That depth is exactly why its daily range is as consistent as it is: with that much liquidity constantly pricing it, a 60-100 pip day isn't noise from a handful of large orders, it's the genuine result of a very large number of participants disagreeing and resolving that disagreement throughout the session. A thinly traded pair can post a huge range off one lopsided order; EUR/USD generally can't.
What the number is actually useful for
Not for picking a target. A target should come from a measured Fibonacci extension on the last completed swing, not from "the average day moves 80 pips so I'll aim for 80." It's genuinely useful for sanity-checking a stop: a stop placed 5 pips from entry on a pair that routinely moves 60-100 pips a day is going to get clipped by ordinary noise long before the actual thesis is ever tested. A stop needs enough room to be wrong about noise while still being right about the idea, which is the whole reason a real stop is measured from the chart, not picked as a round number.
What moves the number itself
- Session overlap. London/New York overlap (roughly 12:00-16:00 GMT) is consistently where range expands most.
- Scheduled data. A high-impact release can compress the entire rest of the day's range into a single hour, or blow the daily average out entirely.
- Day of week. Monday opens are frequently tighter than mid-week sessions; Friday afternoons often compress into the weekend close.
How this actually shows up in a published plan
None of this changes the underlying method. It's a reason the read gets reset before every session instead of published once and left to apply to conditions that have already changed. A stop and target sized for a quiet Tokyo session and carried unchanged into a volatile New York one is sized for the wrong market. If you want to see the range question answered for a specific day rather than as an average, that's exactly what a real published forecast is doing each time it's measured fresh.